Base Metals
Jubilee’s Zambian Copper Output Jumps as Integration Strategy Takes Shape


By: OrePulse
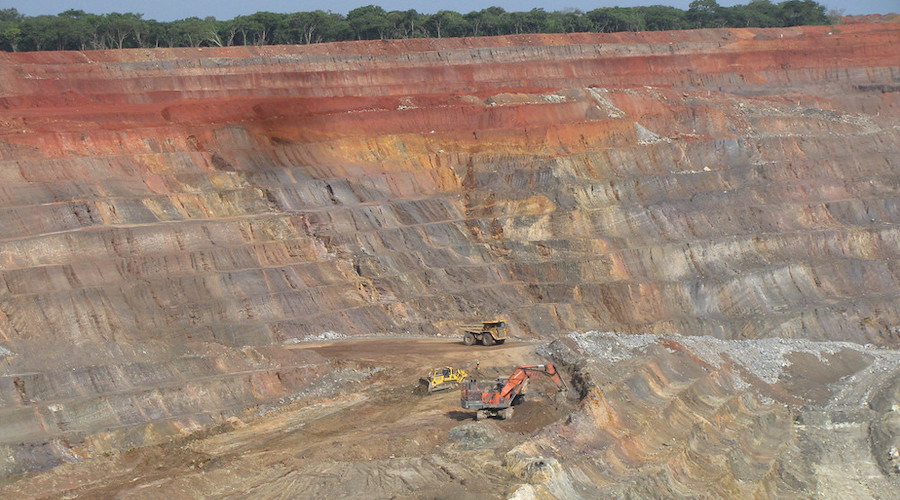
Jubilee Metals Group posted a sharp increase in copper output from its Zambian operations for the fiscal year ending June 30, 2026, as the company continues shifting toward becoming a vertically integrated copper producer.
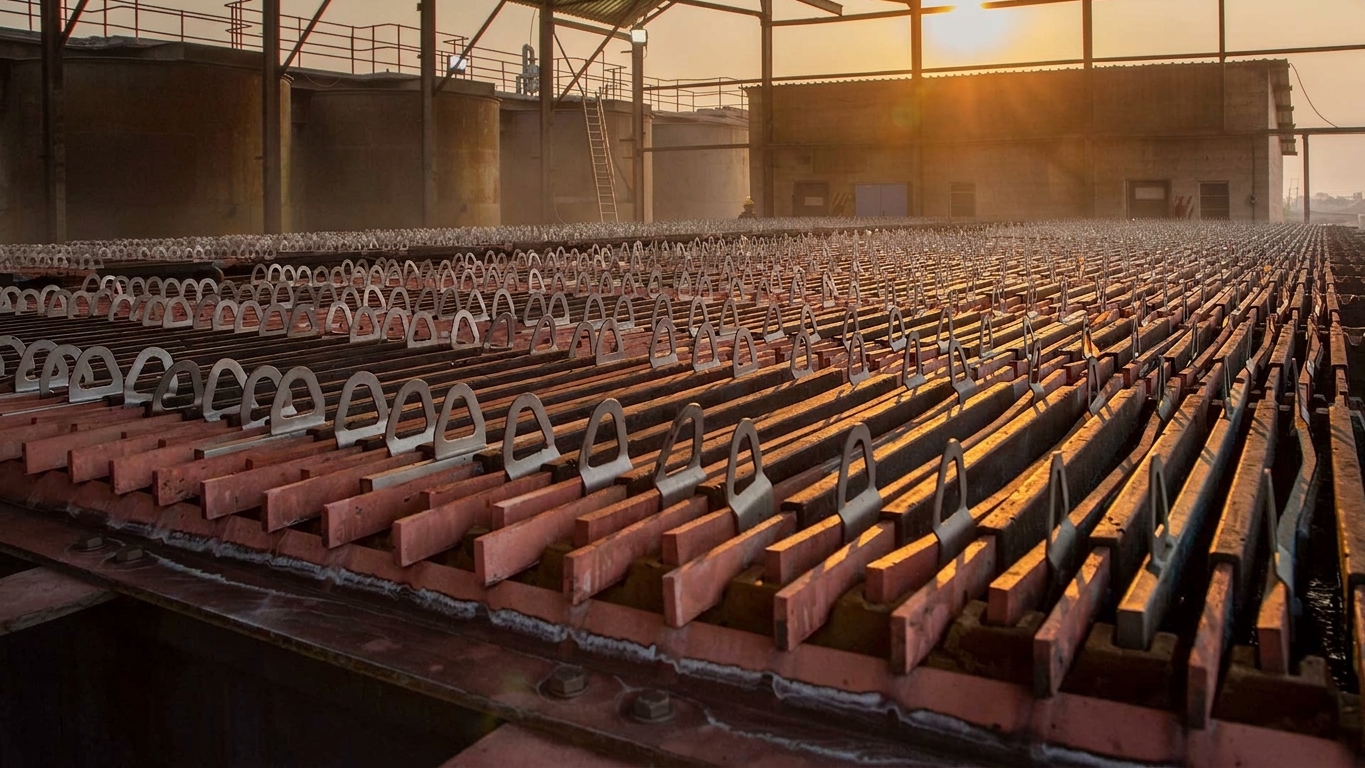
Copper production from the combined Roan and Molefe operations climbed to 3,739 tonnes for the year — a 225% increase over the prior period. The volume of material sent to the company's Sable refinery for processing grew even faster, jumping nearly 15-fold to 1,342 tonnes of contained copper. By contrast, the combined total of cathode and copper sulphide concentrate ready for sale rose only modestly, up 1.3% to 2,120 tonnes, while cathode output specifically at Sable increased 17.5% to 1,207 tonnes.
The fourth quarter brought notable operational challenges. A sharp drop in domestic acid supply within Zambia pushed acid prices up by more than double, and diesel costs rose approximately 90%, pressures significant enough to force temporary shutdowns at some metal-processing facilities.
For the year ahead, the company expects Roan to yield between 2,850 and 3,150 tonnes of copper, based on processing 25,000–30,000 tonnes of feed material monthly at a copper grade of roughly 1.5–1.6%. Molefe's targets are more ambitious: management is aiming for 10,000 tonnes of high-grade run-of-mine material monthly at a 1.45% copper grade, which could yield up to 1,740 tonnes of contained copper annually — though in the nearer term, the goal is to first raise run-of-mine output to 7,000–7,500 tonnes per month. A separate initiative, internally referred to as Project G, is slated to begin development in February 2027.
In a related move, Jubilee agreed to sell its Large Waste project for $35 million (with an accelerated-settlement option at $30 million) and released a $2.25 million deposit held for due diligence. The company is keeping its Tjate platinum-group-metals asset in South Africa, which remains under strategic review.
Together, the production surge and the divestment reflect Jubilee's broader transformation — moving away from its historical role as a processor of third-party material toward building an integrated mine-to-metals operation centered on its Zambian copper assets. Notably, the gap between the 225% rise in combined output and the far more modest 1.3% growth in finished, saleable product suggests the company is still converting only a fraction of the material entering its pipeline into refined copper. Jubilee's FY2027 guidance implies management expects that gap to close as both Roan and Molefe mature toward stable production.
Roan is also the only operation for which Jubilee feels confident publishing forward guidance; forecasts for Molefe and Project G will follow once those sites show more consistent output, reminding investors that much of the company's near-term growth narrative still hinges on assets in early ramp-up phases. Meanwhile, the steep rise in acid and diesel costs during the fourth quarter highlights how exposed Zambian copper producers remain to input-cost swings, even during a period of rising output.
Related Articles
Sanu Gold Announces $5 Million Private Placement L...
06 Sep, 2024 13:08
Ivanhoe Mines produces 40,347 tonnes of copper at ...
09 Sep, 2024 09:21
Andrada partners with SQM to develop Namibia lithi...
10 Sep, 2024 08:56
US, Saudi Arabia in talks to secure metals in Afri...
10 Sep, 2024 09:07
DRC: Eurasian Secures $150 Million to Develop a Co...
12 Sep, 2024 06:22
Zambian mines desperate for power turn to a surpri...
13 Sep, 2024 11:18
Africa at the cusp of a critical minerals boom...
17 Sep, 2024 07:40
Coolabah to unite Broken Hill assets, paving path ...
17 Sep, 2024 08:40
Marula Mining completes first manganese exports sa...
18 Sep, 2024 09:05