Métaux de base
Congo's Copper Exports Hit Record High as Western Sales Double


By: OrePulse
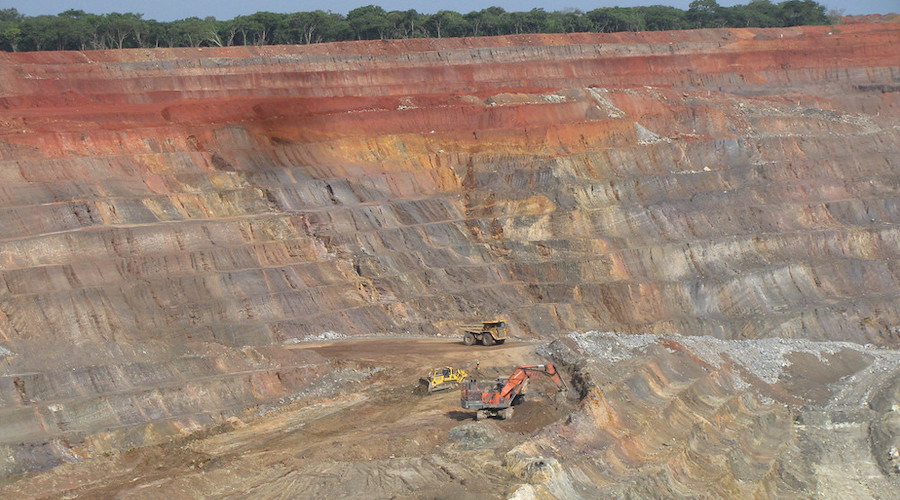
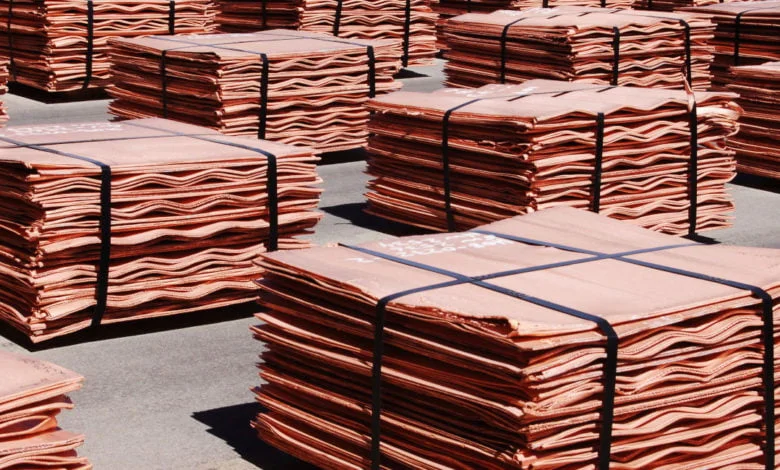
The Democratic Republic of Congo exported a record 1.72 million tonnes of copper in the first half of 2026, up from 1.65 million tonnes over the same period the previous year, driven by sales to the United States and Europe that doubled from year-earlier levels.
This surge follows a strategic minerals partnership Kinshasa signed with Washington in December 2025, under which Congo has pursued what government officials have called an "export diversification offensive" — an effort to reduce the country's reliance on Chinese trade routes for its copper and cobalt exports. While the proportion of copper heading to the U.S. and Europe doubled relative to 2025, the exact tonnages sent to those specific markets were not made public.
State-owned mining company Gecamines has teamed up with commodity trading firms Mercuria and Glencore to help market copper sourced from major Congolese mining operations — including several controlled by Chinese companies — to buyers located outside China. This arrangement is structured to generate extra revenue for Gecamines through its minority ownership stakes in operations such as Tenke Fungurume Mining and Kamoto Copper Company, while simultaneously expanding the range of buyers for Congolese copper beyond its historically China-heavy customer base.
Cobalt told a different story, with exports declining 6.4% to 41,140 tonnes in the first half of 2026, down from 43,930 tonnes during the same period a year prior. This drop stems from export quotas that Kinshasa has placed on the battery metal.
In June, Congo's government banned exports of copper and cobalt concentrate. Even with that restriction in place, concentrate shipments during the first half of the year still reached 151,202 tonnes, containing 50,629 tonnes of copper. Among the top exporters of concentrate during this period were Eurasian Resources Group's Frontier Mining operation, along with Kinsenda Copper Company, Everbright Mining and Sabwe Mining. On the cobalt front, CMOC's Kisanfu mine led cobalt hydroxide exports, shipping 24,825 tonnes in the first half of the year.
Congo's copper and cobalt exports play a critical role in supplying battery, electronics, and construction industries worldwide, with China historically serving as the dominant buyer of — and investor in — the country's mining output. Major companies including CMOC, Huayou Cobalt and Zijin continue to operate significant mining assets within the country.
This shift toward routing more output to Western buyers is unfolding as both the United States and European governments work to secure access to critical minerals through channels not controlled by China, part of a larger strategy to diversify battery and clean-energy supply chains away from dependence on a single dominant buyer. For Kinshasa, stronger commercial ties with buyers in Washington and Europe offer a path to diversify export revenue and attract new investment into its mining sector — even as Chinese companies continue to hold substantial operating interests in the country's largest copper and cobalt mines.
These record export figures arrive as global copper demand remains robust, fueled by electrification trends, data-center construction, and investment in power grid infrastructure — all of which continue to pressure major producing nations to ramp up output and secure the trade relationships and logistics networks needed to get material to market.
The involvement of Glencore and Mercuria alongside Gecamines stands out because both trading firms already maintain extensive commercial relationships tied to Congolese copper and cobalt production, giving the state miner well-established pathways to direct additional volumes toward U.S. and European buyers without needing to construct entirely new trading relationships. For Gecamines specifically, this arrangement also helps it capture more value from its minority stakes in Chinese-operated projects like Tenke Fungurume Mining and Kamoto Copper Company by taking a more hands-on role in marketing that output rather than relying solely on its operating partners.
The contrast between rising copper exports and declining cobalt shipments highlights how these two metals—despite often coming from the same Congolese ore deposits—are shaped by very different regulatory and market forces. Copper has benefited from strong global demand alongside the country's new push toward Western buyers. At the same time, cobalt remains constrained by the government's quota system, introduced to support prices after years of oversupply. The June ban on unprocessed concentrate exports adds yet another layer of policy aimed at capturing more processing value domestically, even though substantial volumes of concentrate continued moving through the export system during the first half of the year.
Congo's strategic pivot comes as Western governments actively court African producers of critical minerals, as part of broader efforts to reduce dependence on Chinese-dominated supply chains for battery materials and clean-energy inputs. The December 2025 partnership with Washington provides a formal government-to-government structure for this effort, while the participation of established commodity trading firms offers a practical route actually to bring product to market. Whether the doubling in Western sales volumes recorded during the first half of 2026 can be sustained going forward will likely hinge on continued demand from buyers in the U.S. and Europe, as well as Kinshasa's ability to keep expanding its export capacity as it pushes forward with this diversification strategy.
Articles similaires
Sanu Gold Announces $5 Million Private Placement L...
06 sept., 2024 13:08
Ivanhoe Mines produces 40,347 tonnes of copper at ...
09 sept., 2024 09:21
Andrada partners with SQM to develop Namibia lithi...
10 sept., 2024 08:56
US, Saudi Arabia in talks to secure metals in Afri...
10 sept., 2024 09:07
DRC: Eurasian Secures $150 Million to Develop a Co...
12 sept., 2024 06:22
Zambian mines desperate for power turn to a surpri...
13 sept., 2024 11:18
Africa at the cusp of a critical minerals boom...
17 sept., 2024 07:40
Coolabah to unite Broken Hill assets, paving path ...
17 sept., 2024 08:40
Marula Mining completes first manganese exports sa...
18 sept., 2024 09:05